Grant Tracking Audit Trail: Expenditure Spreadsheet Structure That Holds Up
How to keep a grant tracking audit trail in a grant expenditure spreadsheet: one tab per award, a summary tab, a dated change log, source records and monthly close checks.
In this article (9)
- Quick Answer: How Do You Keep a Grant Tracking Audit Trail in a Spreadsheet?
- What a Grant Expenditure Tracking Spreadsheet Is
- Nonprofit Grant Tracking in a Single Workbook
- Grant Tracking Audit Trail Inside an Expenditure Spreadsheet
- The Summary Tab That Rolls Up All Awards
- Nonprofit Grant Tracking Software: When the Workbook Stops Being Enough
- Keeping Your Expenditure Spreadsheet Audit Ready
- FAQ
- Load the First Award Before the Next Month End
A grant expenditure tracking spreadsheet records what you spent, on which award, against which approved line, and where the receipt lives. The grant tracking audit trail behind it, meaning who entered each line, what changed and which document proves it, is what turns that file into evidence. A single sheet that grows one column at a time eventually breaks. Structure decided up front prevents that.
An expenditure tracker is a workbook that ties every spending line to an award record and a source document. The layout here uses one tab per award plus a summary tab, the same structure as the free workbook, with each block tied to the federal record rule it serves.
Quick Answer: How Do You Keep a Grant Tracking Audit Trail in a Spreadsheet?
A grant tracking audit trail in an expenditure spreadsheet comes from three habits: a source file name on every spending row, a dated change log on each award tab, and months locked after reconciliation so corrections post as new rows. Built-in spreadsheet history is partial, so the manual log carries the record of who changed what.
Free download: Grant expenditure tracking workbook (one tab per award plus summary) as Excel .xlsx. No email address required.
What a Grant Expenditure Tracking Spreadsheet Is
A grant expenditure tracking spreadsheet is a post award ledger that answers four questions for every dollar: which award paid, what the cost was for, whether the award terms allow it, and what document proves it. A row that cannot answer all four is incomplete.
Federal rules in the Uniform Guidance at 2 CFR 200 set the floor. 2 CFR 200.302(b)(3) requires "Maintaining records that sufficiently identify the amount, source, and expenditure of Federal funds for Federal awards," and adds that "All records must be supported by source documentation" (eCFR 2 CFR 200.302(b)(3), current as of September 2026). A second paragraph requires every recipient system to provide for "Comparison of expenditures with budget amounts for each Federal award" (eCFR 2 CFR 200.302(b)(5), current as of September 2026). The workbook exists to meet those two sentences.
A third rule shapes the header of each award tab. 2 CFR 200.302(b)(1) requires "Identification of all Federal awards received and expended and the Federal programs under which they were received," including the Assistance Listings title and number and the Federal award identification number (eCFR 2 CFR 200.302(b)(1), current as of September 2026). Put those identifiers at the top of every award tab, in the same place on every tab, so a reviewer opening any sheet finds the award number without hunting.
In one Reddit thread about building a grant tracker, three commenters laid out the same shape: one tab per grant plus a summary tab that pulls from them, one of them suggesting the name "Dashboard" (Reddit thread 1qx3lpf, read September 2026). A commenter in a separate thread named the failure that follows: "several people have hard coded some numbers and it's a train wreck now" (Reddit thread 1vmiey8, read September 2026). Formulas pull from entry rows. Entry rows link to source files. No one types over a formula.
Our day-one award checklist covers what to capture so the tracker starts with correct identifiers.
Nonprofit Grant Tracking in a Single Workbook
Nonprofit grant tracking in a single workbook works when one file holds every active award in the same shape. Each award tab carries the same blocks in the same order, so a new hire can read any tab without a tour.
Start each award tab with an identity block. Include the funder name, program name, award number, period of performance with start and end dates, the as-of date, reporting cadence from the agreement, payment method, the approved total, the next report and draw dates, and the contact for approvals. For foundation awards, use the grant reference from the award letter in the same position.
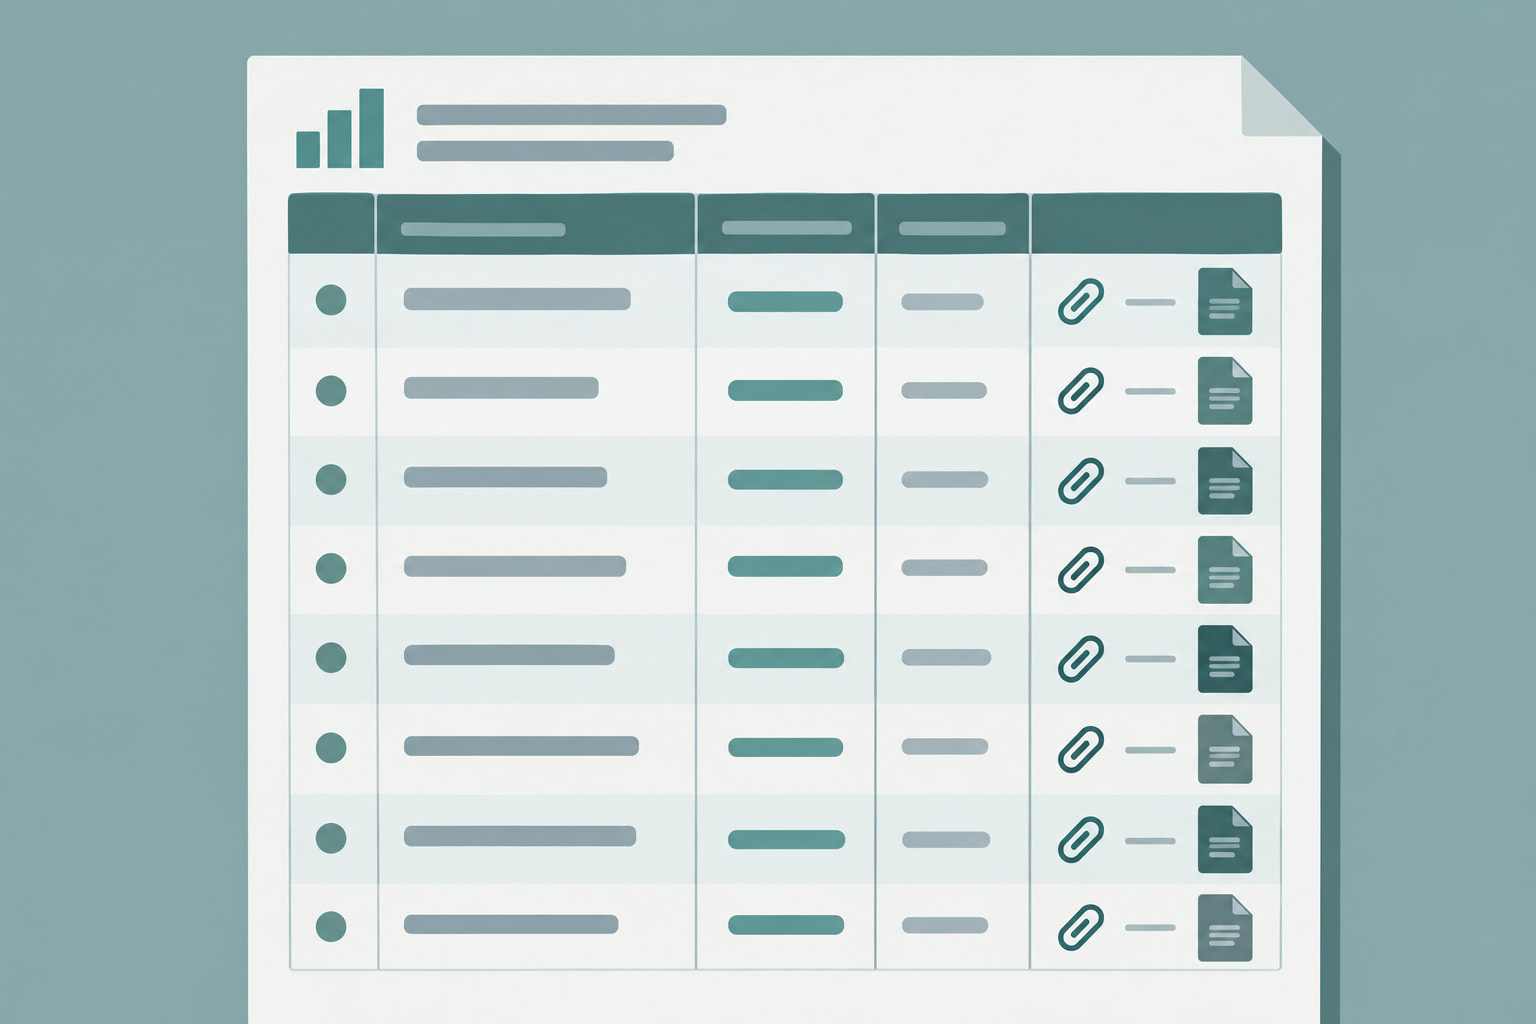
Below identity comes the spending log. One row per transaction. Date paid, vendor or payee, short purpose, approved line name, amount, funding source, payment reference, and source file name. Use the approved line names from the funded budget, word for word. Under the log, a spending-by-line block sums each approved line from the log and compares it with the approved amount. For the pre-award side, see the grant tracking spreadsheet template.
Approval and Allowability Notes
Add two narrow fields to each spending row: who approved the charge and why it is allowable under the award terms. The discipline comes from 2 CFR 200.403, which lists the eight criteria a cost must meet to be allowable, beginning with "(a) Be necessary and reasonable for the performance of the Federal award and be allocable thereto under these principles" (eCFR 2 CFR 200.403, current as of September 2026).
Consistent treatment needs its own check. 2 CFR 200.403(d) requires consistent treatment in that "a cost must not be assigned to a Federal award as a direct cost if any other cost incurred for the same purpose in like circumstances has been allocated to the Federal award as an indirect cost" (eCFR 2 CFR 200.403(d), current as of September 2026). A further rule bars double use of the same cost. 2 CFR 200.403(f) bars a cost from being "included as a cost or used to meet cost sharing requirements of any other federally-financed program in either the current or a prior period" (eCFR 2 CFR 200.403(f), current as of September 2026).
Staff Charges Without Timesheet Fiction
Staff time is usually the largest line and the weakest record. Post salary charges by pay period with the employee name, the share charged to the award, and the record that supports the share. The standard is direct: 2 CFR 200.430(g)(1) requires that "Charges to Federal awards for salaries and wages must be based on records that accurately reflect the work performed" (eCFR 2 CFR 200.430(g)(1), current as of September 2026). Estimates alone fail that test, because 2 CFR 200.430(g)(1)(vii) states that "Budget estimates (meaning, estimates determined before the services are performed) alone do not qualify as support for charges to Federal awards, but may be used for interim accounting purposes" under three stated conditions (eCFR 2 CFR 200.430(g)(1)(vii), current as of September 2026).
Grant Tracking Audit Trail Inside an Expenditure Spreadsheet
A grant tracking audit trail is a record that shows who entered each spending line, when the entry changed, and what source document supports it. Without that trail, a spreadsheet is a claim. With it, the same file becomes evidence.
One commenter in a thread about grant software said a spreadsheet "can't nag anyone" and "keeps no record of who changed what" (Reddit thread 1vydvxu, read September 2026). The second claim is only partly true, and the gaps are what matter in an audit.
Excel for Microsoft 365 has Show Changes, which shows "who changed what, where, and when," but "for up to 60 days," skips formatting and PivotTable changes, and has a reset that clears the history "for everyone using this workbook" (Microsoft Support, read September 2026). Google Sheets warns that "Some changes might not show up in the edit history," including added or deleted rows and changes made by formulas (Google Docs Editors Help, read September 2026). A history that expires, misses deleted rows and can be wiped is a convenience, not a grant tracking audit trail.
Give every award tab a change log at the bottom. Date, editor role, row or cell changed, old value, new value, reason. Lock prior months once reconciled so corrections post as new rows with a reversal reference instead of overwriting history. The same record habits belong on a compliance checklist for federal grants.
This is the layout of the free workbook, which also opens with a Read Me tab; the record requirements behind it sit in 2 CFR 200.302(b) (eCFR, current as of September 2026).
Cost movement rules belong in the trail. A cost allocable to one federal award may not be charged to other federal awards to overcome fund deficiencies or to avoid restrictions in statutes, regulations or award terms (eCFR 2 CFR 200.405(c), current as of September 2026). A cost that benefits several awards in proportions that can be determined without undue effort or cost must be allocated on the proportional benefit (eCFR 2 CFR 200.405(d), current as of September 2026). Record the base on the row: headcount share, square footage share, or usage log.
The Summary Tab That Rolls Up All Awards
The summary tab is the one page a director reads. It rolls up every award tab into approved totals, spending to date, remaining balances, burn pace, and status. It contains no manual totals: every cell is a formula reading an award tab, including the next report and draw dates, which are typed once in each award tab's identity block.
Stagger is the hard part. One commenter describing multi-grant tracking named it: "the grant periods start and end at all different times" (Reddit thread 1vmiey8, read September 2026). The summary handles that with three date fields per award: period end, next report due, and next draw or invoice date. Sort by nearest date, not by award size, because each award is a repeating schedule of reports, not one deadline.
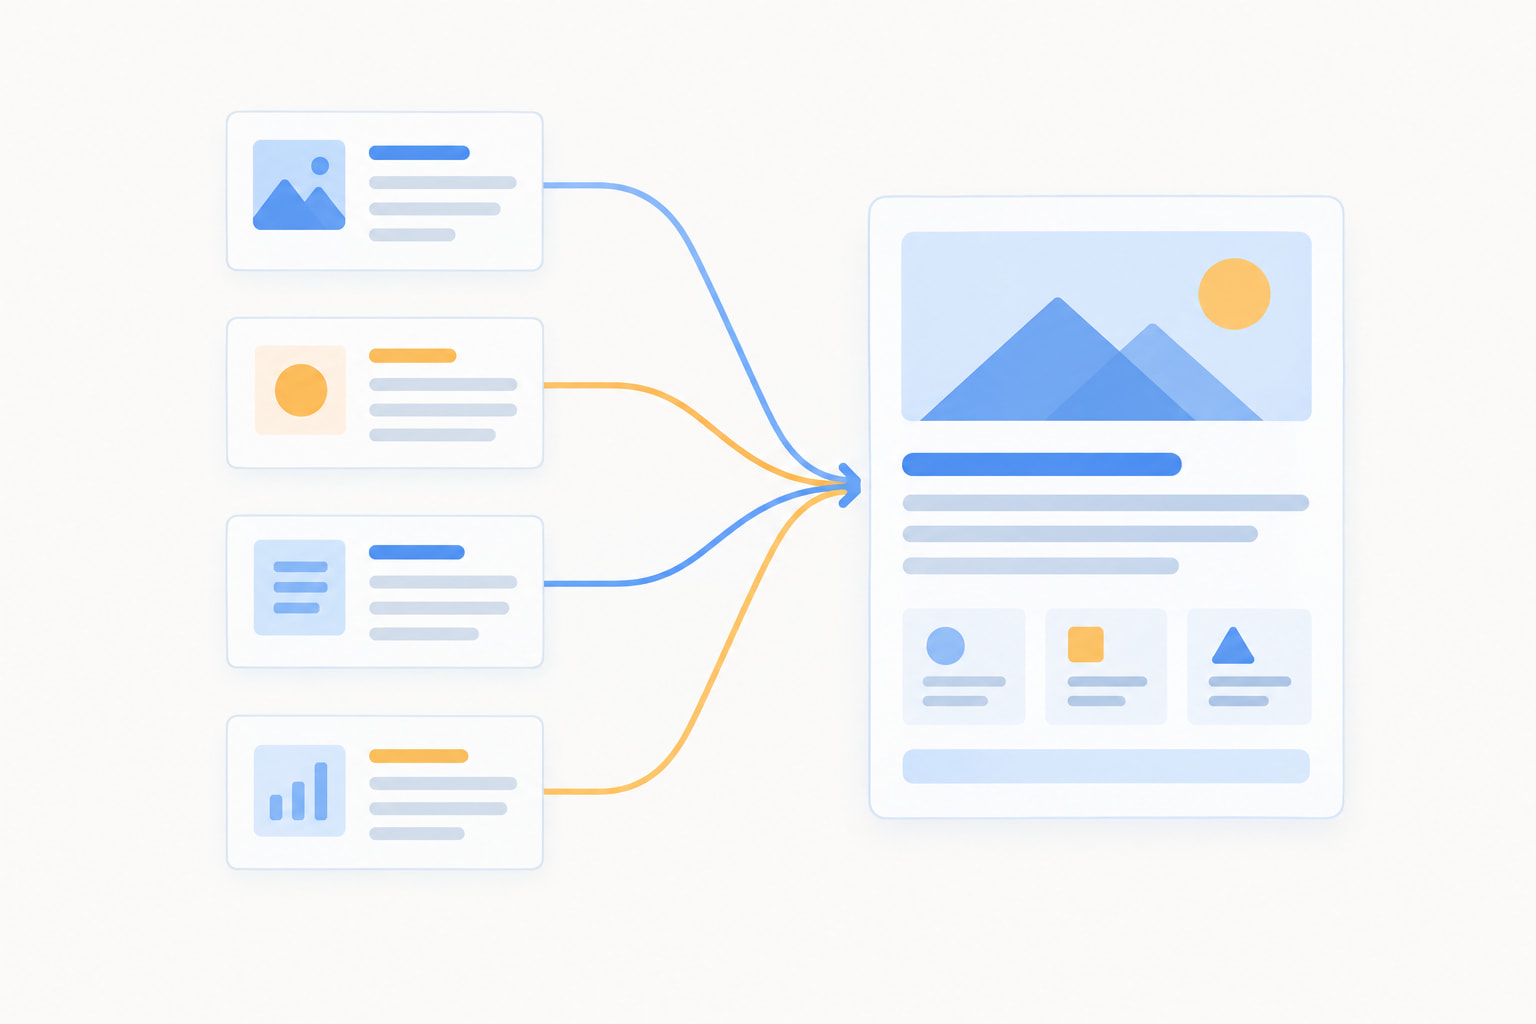
Keep the rollup to one row per award. The download's summary carries approved total, spent to date, remaining, percent used, period elapsed, burn pace, the indirect or allowance line, the three dates, payment method and status. Status uses a fixed vocabulary: on pace, watch, at risk, closed.
Indirect costs need a visible line on both the award tab and the summary. The download's foundation award carries an administrative allowance set by its award letter in place of an indirect rate, and the summary column is labeled for both so the two are never blended. Recipients and subrecipients without a current federally negotiated rate "may elect to charge a de minimis rate of up to 15 percent of modified total direct costs (MTDC)" (eCFR 2 CFR 200.414(f), current as of September 2026). MTDC itself "means all direct salaries and wages, applicable fringe benefits, materials and supplies, services, travel, and up to the first $50,000 of each subaward (regardless of the period of performance of the subawards under the award)" (eCFR 2 CFR 200.1, current as of September 2026).
Mark each award as advance or reimbursement. Under reimbursement the agency or pass-through entity "must make payment within 30 calendar days after receipt of the payment request unless [it] reasonably believes the request to be improper" (eCFR 2 CFR 200.305(b)(3), current as of September 2026). Cash planning follows from that field.
This is the filing scheme on the download's Source Records tab. The underlying rules are 2 CFR 200.302(b)(3) on source documentation and 2 CFR 200.430(g)(1) on payroll records (eCFR, current as of September 2026).
Nonprofit Grant Tracking Software: When the Workbook Stops Being Enough
Nonprofit grant tracking software is a database that replaces the workbook when volume or scrutiny outgrows manual checks.
Churn is the first warning sign. One commenter reports "my organization has had about 400 versions of a grant tracker" (Reddit thread 1qx3lpf, read September 2026), and the same thread puts the underlying need as "what they want is a database, not a spreadsheet" (Reddit thread 1qx3lpf, read September 2026). Read together, they point to a cycle: a workbook built around one person, rebuilt by the next hire, abandoned within months, the pattern behind why grant trackers fail.
Two conditions mark the switch point. The first is split-funded payroll. Where staff are paid from several awards, the check that records must not exceed "100 percent of compensated activities" has to hold every pay period, for every employee (eCFR 2 CFR 200.430(g)(1)(iii), current as of September 2026). The second is audit exposure: "A non-Federal entity that expends $1,000,000 or more during the non-Federal entity's fiscal year in Federal awards must have a single or program-specific audit conducted for that year" (eCFR 2 CFR 200.501(a), current as of September 2026). A workbook that cannot reproduce a full year of spending by award, with the source record behind every row, becomes a problem the month that audit starts.
Software does not remove the record rules, but it can enforce them. Approvals, locked periods, and user stamped edits replace the manual change log, and the system keeps the history instead of a person. Reminders replace the habit of opening the file to find a due date. The grant management software guide for nonprofits compares the options, and why grant teams are leaving spreadsheets covers the switch itself.
Keeping Your Expenditure Spreadsheet Audit Ready
Keeping your expenditure spreadsheet audit ready means closing each month the same way, with the same checks, signed by the same roles. Auditors sample months, not intentions. A clean close beats a clever layout.
Run a fixed close within days of month end. Reconcile each award tab to the general ledger. Confirm every row carries a source file name. Confirm the summary pulls cleanly with no broken references. Confirm payroll shares total a full workload, because payroll records must not exceed "100 percent of compensated activities" for the employee (eCFR 2 CFR 200.430(g)(1)(iii), current as of September 2026).
Certification language governs the reports that flow from the tracker. 2 CFR 200.415(a) requires every financial report to carry a certification "signed by an official who is authorized to legally bind the recipient" stating the report "is true, complete, and accurate, and the expenditures, disbursements and cash receipts are for the purposes and objectives set forth in the terms and conditions of the Federal award" (eCFR 2 CFR 200.415(a), current as of September 2026).
Close timing ties to award end rules. A recipient must "submit all reports (financial, performance, and other reports required by the Federal award) no later than 120 calendar days after the conclusion of the period of performance," and a subrecipient must submit its reports to the pass-through entity "no later than 90 calendar days" (eCFR 2 CFR 200.344(b), current as of September 2026). The same section requires a recipient to "liquidate all financial obligations incurred under the Federal award no later than 120 calendar days after the conclusion of the period of performance," with 90 calendar days for a subrecipient (eCFR 2 CFR 200.344(c), current as of September 2026).
These are the checks on the download's Monthly Close tab, which counts how many are signed off; they produce the records 2 CFR 200.302(b)(3) requires (eCFR, current as of September 2026).
Every row in that table is signed by hand, and the report-readiness check depends on someone remembering the date. GrantCue puts award deadlines on an ICS calendar feed with simple email reminders on every plan, Free included. "Post-award lite" budget versus actuals and payment schedules start on the Team plan at $109 a month, and audit trails for status and deadline changes, custom roles and full spenddown tracking start on the Organization plan at $229 a month, while the spending ledger stays in your accounting system and workbook (grantcue.com pricing, October 2026). Compare what each GrantCue plan includes before the next close.
FAQ
What Is a Grant Expenditure Tracking Spreadsheet?
A grant expenditure tracking spreadsheet is a workbook with one tab per award plus a summary tab. Each award tab records actual spending by approved line with the source document named on the row. The summary tab pulls approved totals, spending to date, and remaining balances across awards with no manual totals.
What Is a Grant Tracking Audit Trail?
A grant tracking audit trail is the history behind the numbers: who entered each line, what changed, when it changed, and what document supports it. In a workbook it takes the form of a dated change log, locked prior months, and file names on every row that point to invoices, approvals, and payroll records.
Does Excel or Google Sheets Keep an Audit Trail?
Both keep partial history. Excel's Show Changes records who changed what, where and when for up to 60 days, skips formatting and PivotTable changes, and can be cleared for everyone using the workbook (Microsoft Support, read September 2026). Google Sheets' cell edit history can miss added or deleted rows and changes made by formulas (Google Docs Editors Help, read September 2026). Neither replaces a dated change log with a reason column and locked months.
How Does Nonprofit Grant Tracking Work in a Small Team?
Nonprofit grant tracking works when program and finance staff share one workbook with fixed roles. Program staff post purpose and approval notes. Finance staff post amounts, reconcile to the ledger each month, and lock the period. A director reads the summary tab for burn pace and upcoming reports.
What Is Nonprofit Grant Tracking Software?
Nonprofit grant tracking software is a database tool that holds awards, spending, documents, tasks, and deadlines in linked records instead of workbook tabs. It adds user stamped history, access control, and reminders. Teams adopt it when award count, payroll splits, or audit exposure make manual checks slower than the work they protect.
Can a Spreadsheet Handle a Single Audit Year?
It can if every row carries its source record and each month closes the same way. A single audit applies once an entity expends $1,000,000 or more in federal awards in a fiscal year (eCFR 2 CFR 200.501(a), current as of September 2026), and auditors sample months, so a workbook with a dated change log, locked periods and a source file name on each row can reproduce the year. The strain shows when split-funded payroll turns the payroll total check into a monthly chore.
Load the First Award Before the Next Month End
Start with the award whose next report is due soonest. Load its identity block from the award notice, copy its approved lines word for word, post every transaction since the period start with a source file name on each row, and run the tie-out check before the first close. Then reconcile to the ledger, lock the month, and add the next award tab the same way, so the next report pulls from closed months instead of from memory.